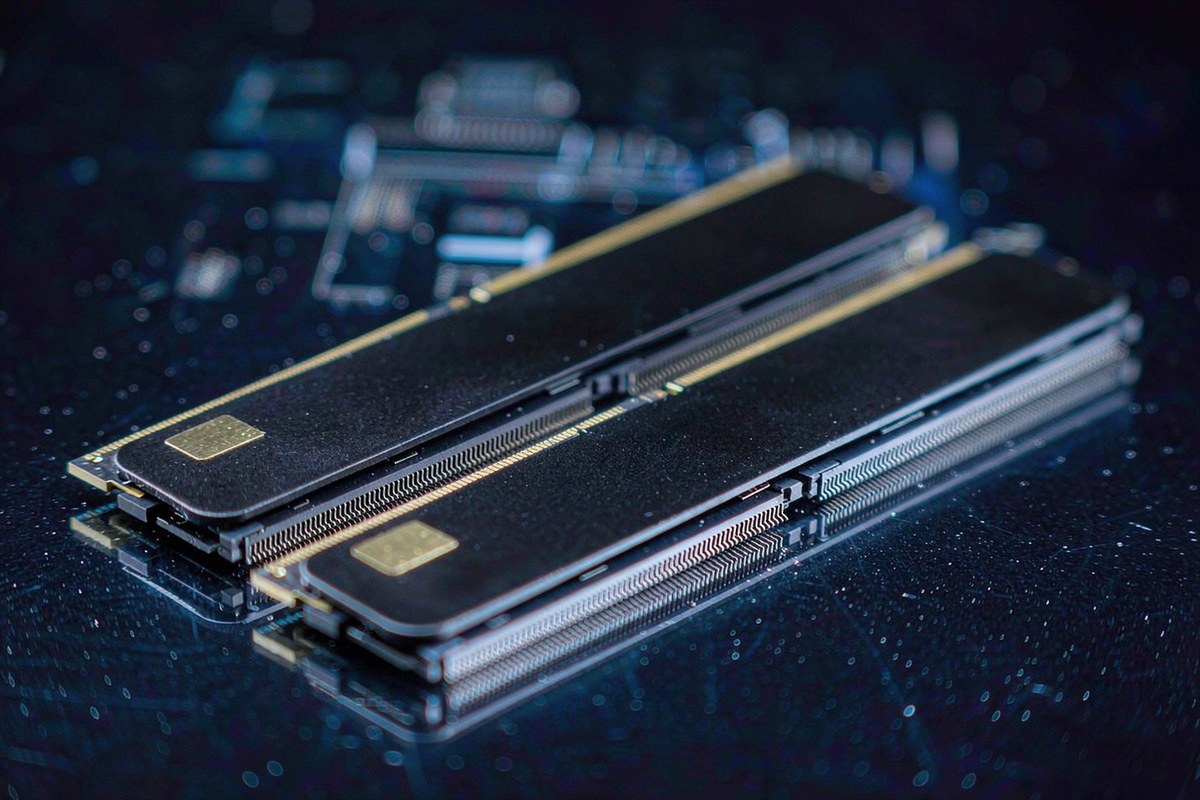
Memory foundries are continuing to prioritize High Bandwidth Memory output over conventional DDR5 modules, a structural shift that is tightening standard server DRAM supply heading into the 2026 second half.
HBM3E and emerging HBM4 stacks deliver materially higher margins per wafer than DDR5 RDIMMs, so the largest DRAM suppliers are steering advanced-node capacity toward AI accelerators. That reallocation is reducing the effective output available for data-center RDIMMs even as enterprise refresh demand stays firm.
For wholesale buyers, the practical effect is rising contract prices and longer lead times on high-density DDR5 modules. Securing frame agreements and mixed-speed allocations now is the most reliable way to protect 2026 delivery slots.
TradingLink maintains direct tier-one allocations for Samsung, SK Hynix and Micron DDR4/DDR5 server memory, with verified, warranty-backed modules available for mixed-capacity and mixed-speed orders across our global partner network.